
The rupee’s movement will also depend on foreign portfolio investor (FPI) flows into domestic equities, which have supported the currency in November. Uncertainty surrounding a possible agreement to end the US-Iran conflict is expected to weigh on India’s currency and bond markets this week.
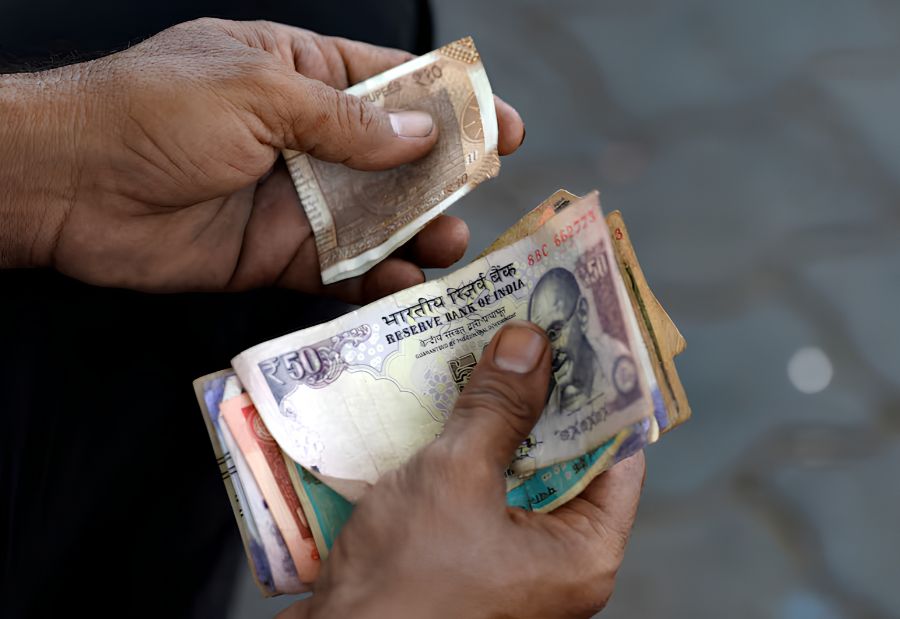
The Indian rupee closed at 94.24 last week, declining 0.4% from the previous week. Its recovery lost momentum following a rise in US bond yields and global oil prices. Geopolitical tensions escalated over the weekend, with Bahrain reporting the interception of Iranian aerial attacks and Tehran claiming to have struck a US military base in the Gulf kingdom.
Strong foreign investments in Indian equities have provided some support to the rupee despite high bond yields, elevated energy prices and expectations of faster interest rate hikes by the US Federal Reserve.
Market participants will closely examine the minutes of the Fed’s latest meeting, scheduled for Wednesday, for signals on inflation risks and future borrowing costs. ING noted that financial markets have revised their expectations of Fed policy following hawkish comments from officials and higher-than-expected core consumer price inflation. The firm expects a 25-basis-point hike next month, while seeing limited chances of a larger 50-basis-point increase.
In India, October wholesale inflation data is due on Monday. This follows a consumer inflation reading that crossed the Reserve Bank of India’s (RBI) upper tolerance limit of 6%. Krishna Bhimavarapu, APAC economist at State Street Investment Management, attributed the increase to risks from a strong El Niño, elevated global oil prices and rising inflationary pressures. He also pointed to geopolitical risks, global monetary tightening and an erratic monsoon as factors supporting an early policy response from the RBI.
Government bonds may continue to face selling pressure as investors assess inflation trends and their potential impact on central bank decisions. Traders expect the benchmark 10-year government bond yield to move between 7.22% and 7.37%. The yield rose 12 basis points last week to 7.3079%, ending 2 consecutive weeks of decline.
The RBI is scheduled to announce its policy decision on December 4, followed by the US Federal Reserve on December 9. While market expectations currently point towards a 25-basis-point hike by both central banks, the possibility of a larger Fed increase remains a concern for bond investors.
Sachin Bajaj, Chief Investment Officer at Axis Max Life Insurance, said his base case was for cumulative rate hikes of 50–75 basis points, taking the terminal rate to 6.00%–6.25%. He added that markets may be factoring in more rate increases than are likely due to global economic risks.
Also read: Viksit Workforce for a Viksit Bharat
Do Follow: The Mainstream LinkedIn | The Mainstream Facebook | The Mainstream Youtube | The Mainstream Twitter
About us:
The Mainstream is a premier platform delivering the latest updates and informed perspectives across the technology business and cyber landscape. Built on research-driven, thought leadership and original intellectual property, The Mainstream also curates summits & conferences that convene decision makers to explore how technology reshapes industries and leadership. With a growing presence in India and globally across the Middle East, Africa, ASEAN, the USA, the UK and Australia, The Mainstream carries a vision to bring the latest happenings and insights to 8.2 billion people and to place technology at the centre of conversation for leaders navigating the future.